How Your Insurance Might Cover Water Damage
Homes can require water damage restoration due to a variety of causes and many homeowners think that their insurance providers will cover the cost of water damage. However, homeowner’s insurance may not cover the cost of water damage as the amount of coverage depends on the cause of the damage. The following are the most common causes of water damage in homes and how a local insurance company may cover them.
Pipe Burst
If a pipe in your home bursts and causes a leak, most of the damage will typically be covered by the homeowner’s insurance. The insurance will cover the water damage caused to the house frame, surrounding walls, and any personal property but basic homeowner’s insurance may not cover the damage to the pipes themselves. If the insurance company decides that your pipes burst due to negligence, they could deny your claim. It is important to control the temperature of your home during the winter or insulate your pipes so that the insurance company is more likely to accept your claim.
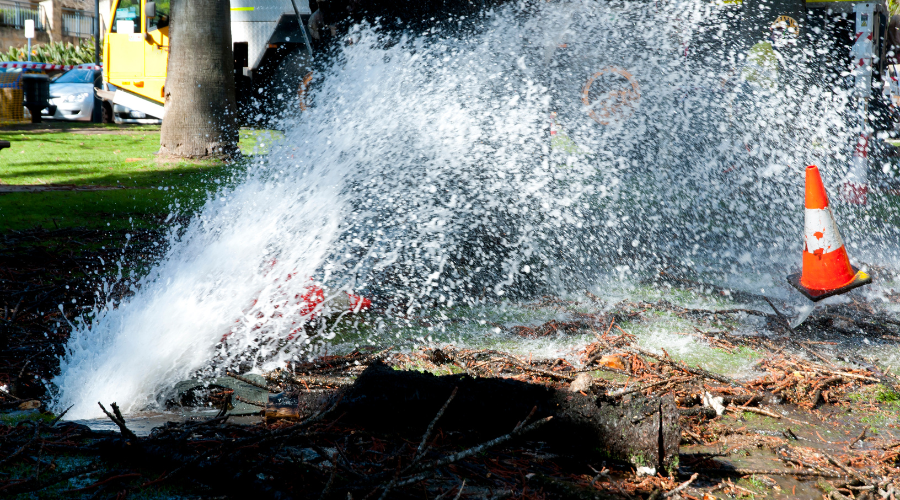
Pipe Burst is a major problem for homeowners. Discover the steps to take to fix your burst drain pipe or find out if it’s time to replace it with a new one.
Washing Machine Leak
Leaks from the washing machine are one of the most common sources for water damage and most washing machine leaks are caused by a leak in the main supply hose that connects the machine to the water supply. In cases involving washing machine leaks, the insurance company will take the age and condition of the machine into consideration and if they determine the leak was the result of regular wear and tear, they may not cover the damages. It is important to make sure your washing machine is repaired if you notice any problems so that you are eligible for coverage if it leaks.
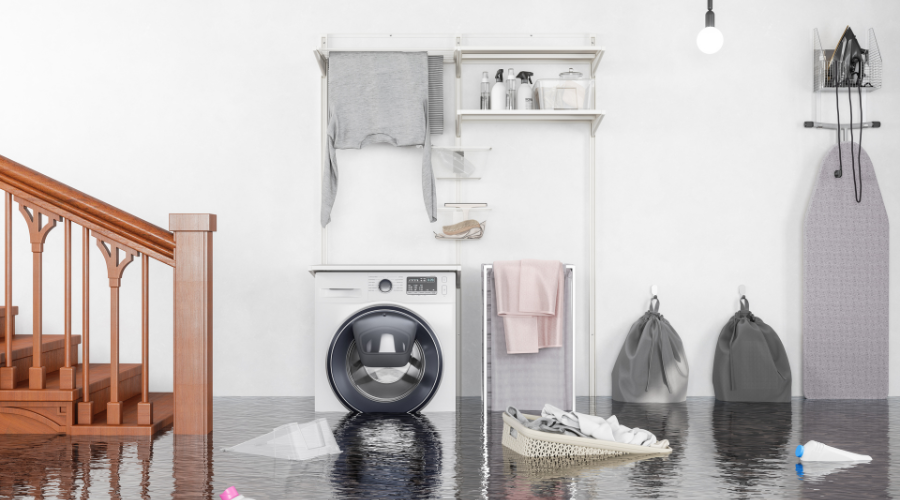
Washing Machine Leak is usually caused by the washing machine hose at the base of your washing machine, or in other cases a leak might occur where the water supply line connects to your washer.
Roof Leaks
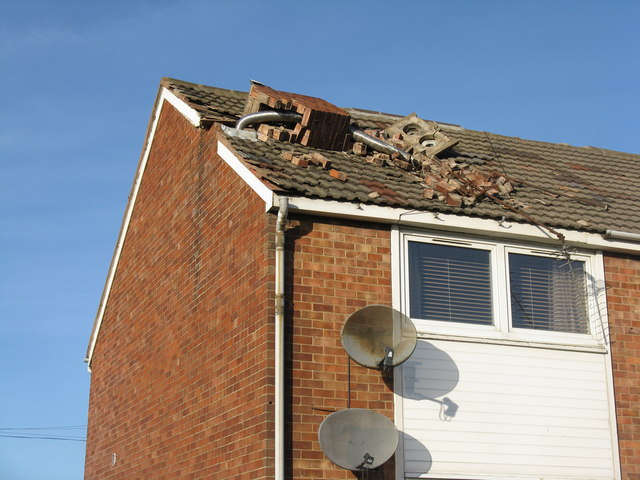
The exact terms of your insurance policy will determine whether or not water damage caused from a roof leak will be covered. To receive coverage, your policy must cover the peril that caused the leak such as rain, wind, fire, or hail. If your insurance policy does not cover the specific peril or the insurance agent determines that your roof is old and needs replacement, they will not cover the damage.
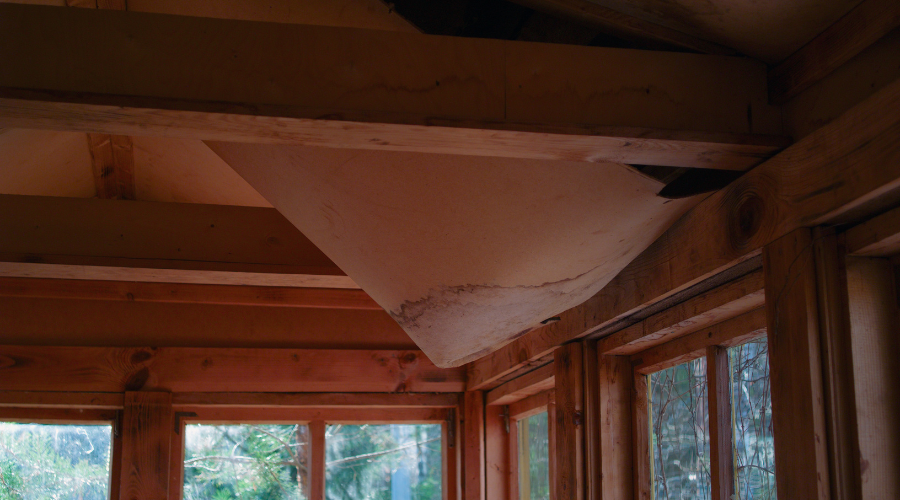
Roof leaks are one of the most common home issues that can damage your property, allowing in unwanted water, debris and insects, while also lowering the value of your home.
Storms or Hurricanes
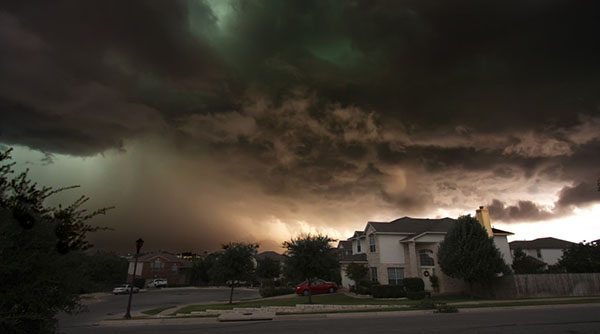
Most typical homeowner’s insurance policies do not cover damage caused by floods regardless of whether the flood was caused by a storm or hurricane. Coverage for flood damage has to be bought separately from the government or a private insurance provider. Without separate flood insurance, you will have to pay for flood damages out of your own pocket but if your policy covers wind as a peril, the insurance company will pay for the damages caused by the wind.
If you are worried that your home may be susceptible to water damage from any of these causes, review your homeowner’s insurance policy to see what your insurance provider will cover. If your insurance policy does not cover one of these causes, make sure to take the appropriate actions yourself to help prevent water damage. It is recommended to hire a water damage restoration professional if your home has already suffered from significant water damage.
How Does Homeowner’s Insurance Cover Water Damage?
Your home can suffer property damage in a myriad of ways. However, there is a good chance that damage that occurs in your home will be the result of water. This is because water damage is one of the most common forms of property damage. From natural flooding, and other weather-related events, to pipe leaks and other internal issues, water damage can be sourced in so many ways.
Typical homeowners’ insurance policies do not cover all types of water damage.
No matter what has caused the water damage, it is important to get help for it right away. Water damage is quick to spread and worsen, because porous building materials and furnishings absorb the excess water and moisture and allow it to spread throughout the property.
To cover the damage, homeowners will often look to file an insurance claim. In fact, water damage claims are among the most common insurance claims. However, it’s important to know that water damage will not always be covered by your homeowner’s insurance.
Continue reading to learn more about how homeowner’s insurance covers water damage.
When Is Water Damage Covered by Homeowner’s Insurance?
Whether your home insurance policy covers water damage depends on various factors:
- Your policy
- The source of the damage
- The circumstance of the damage: accidental, sudden, or gradual.
Always take a look at your insurance policy and analyze the wording to see what sorts of damage it will cover. Generally, homeowner’s insurance policies will cover water damage if it happens accidentally or suddenly.
Within the policy, the damage can be covered by either dwelling coverage or personal property coverage. Dwelling coverage takes care of any structural damage to your home, and personal property coverage addresses your damaged personal belongings. But such coverage is covered only if the damage occurred as a result of a covered hazard.
When Is Water Damage Not Covered by Homeowner’s Insurance?
The Water Damage’s Source
Your homeowner’s insurance policy may cover the expenses for building materials and other belongings that were damaged by water. However, it does not cover the source of the water.
For example, a pipe suddenly bursts in your home despite it having proper insulation. As a result, it damages drywall and other building materials. Your homeowner’s insurance will cover the damage it caused to the building materials, but the cost of repairing or replacing the pipe will come out of your own pocket.
Gradual Damage and Lack of Maintenance
Most homeowner’s insurances do not usually cover gradual damage. If this type of damage occurs, and you file a claim for it, then it will likely be denied.
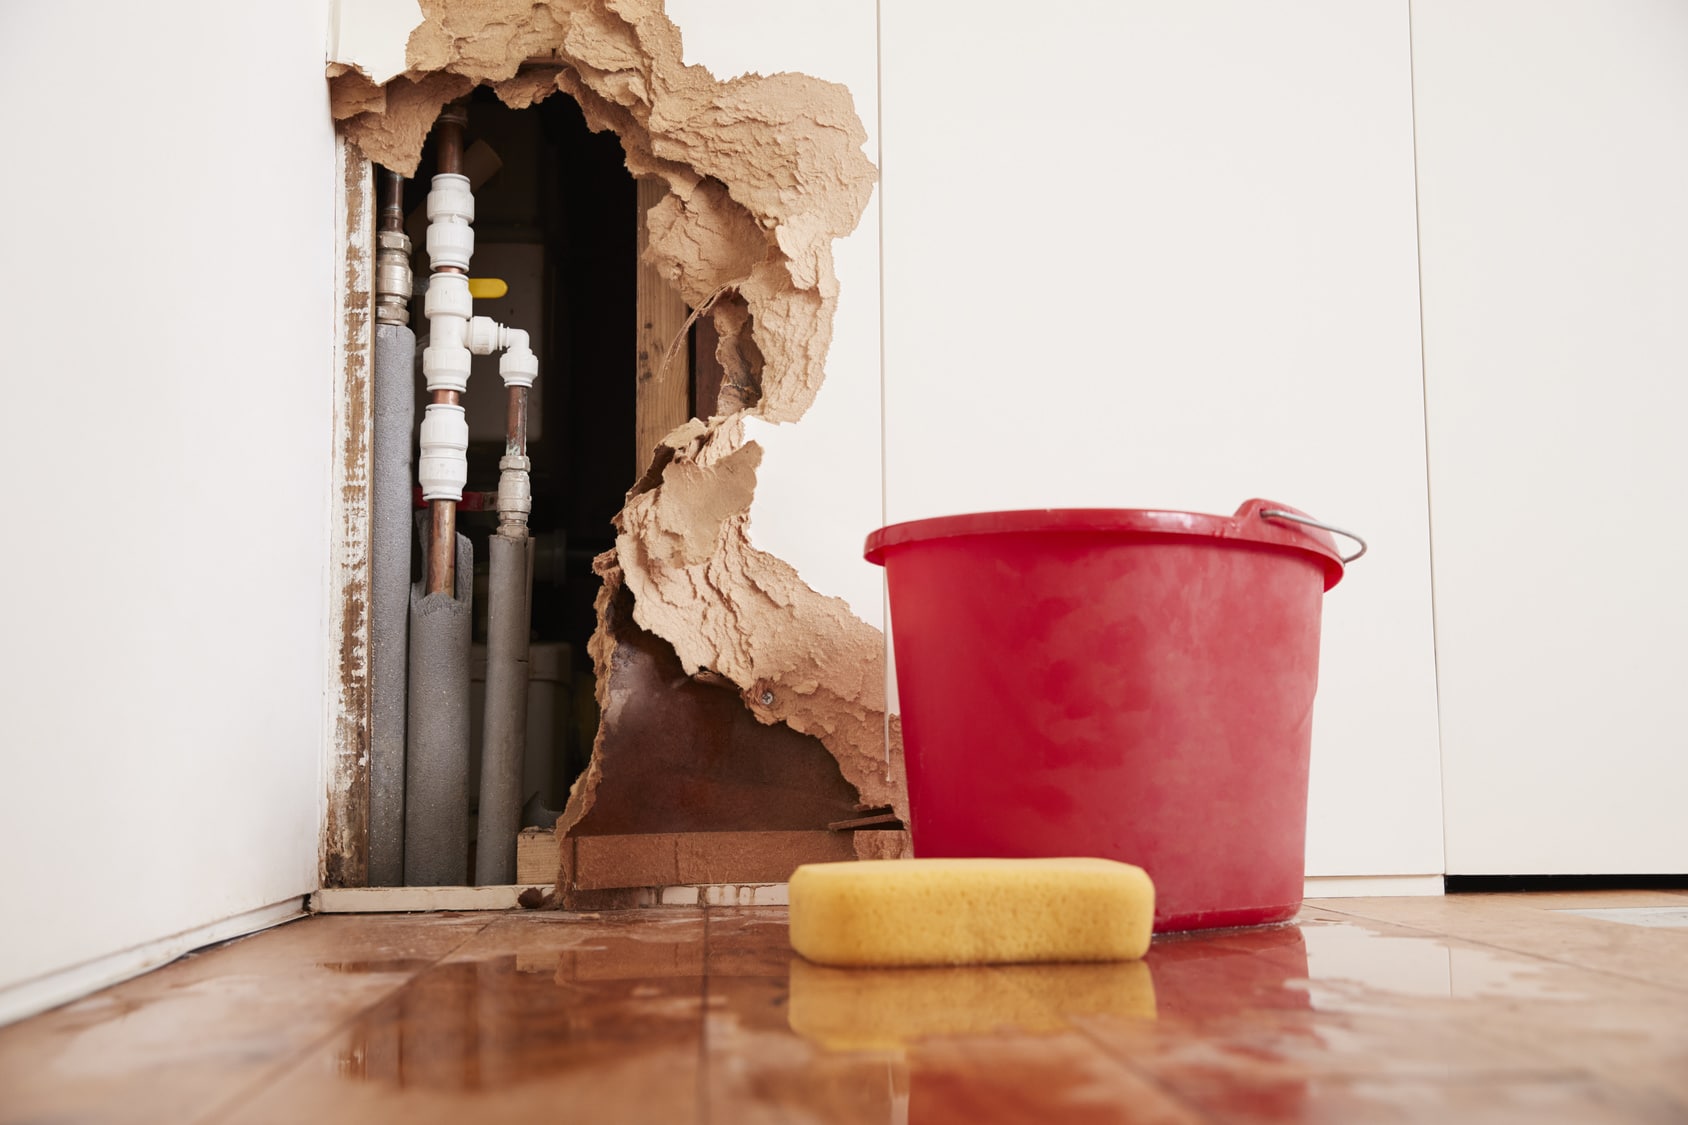
Your homeowner’s insurance policy may not cover water damage that happens by gradual negligence.
Gradual damage is harm that occurs over time, hence the descriptor. You may claim water damage occurred suddenly or accidentally, but this kind of damage needs to be filed right away. Otherwise, time will pass, worsening the damage and re-categorizing it as gradual damage. Because of this, your insurance will not cover this damage. Some examples of gradual damage include water damage from a pipe that has been leaking over time and water damage that occurred due to a failure to repair damaged roofing.
Furthermore, gradual damage can be a result of poor, or even no maintenance. While wear and tear is normal, proper maintenance can prolong the lives and efficiency of items, which is why it’s important to have regular maintenance work done. However, if you failed to maintain items, and issues arise, your insurance company won’t cover the damage.
For example, if your home has a leaky pipe, but you choose to not have it fixed right away, then it is likely it will eventually result in some amount of water damage, and possibly mold growth. An insurance claim for this harm would be denied because the damage could have been prevented with proper maintenance.
Flooding and Water Backups
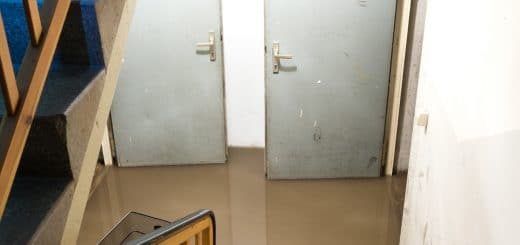
Standard homeowner’s insurance does not provide coverage for any flooding — even if it happened because of a storm or other weather-related event. In order for your insurance company to cover flooding, you will need to buy an additional policy. The same usually goes for water backups caused by outside drains and sewers. If your insurance policy doesn’t cover such a situation, then you will need extra coverage.
Getting Water Damage Restoration Help for Your Home
By knowing how your homeowner’s insurance will cover any need for water damage removal or remediation, you have a greater chance of filing a successful claim, if you do so quickly. Taking immediate action is how you should react to water damage, regardless of insurance claims.
Once water makes its way into your home, it will spread quickly, becoming absorbed by any porous building materials and furnishings. The water will weaken the items, eventually causing serious structural damage. If the water involved in the damage is not clean, meaning it’s gray or black water, then it can result in even more damage.
Because of this, water damage is an emergency that requires prompt help. Reach out to a professional water damage restoration service to handle the repairs and restoration work. Professionals will have the proper equipment and expertise to conduct efficient cleaning and repairs, restoring your home to safe living conditions.
Does Homeowner’s Insurance Cover Water Damage from Rain?
 Unfortunately, there are a number of ways that water damage can cause severe destruction within a home. These sources can include sewer backups, burst and leaking pipes, water leaks, flooding, drain overflows, and rainstorms. As soon as you have discovered that there is a significant amount of damage on your property, don’t hesitate to call a professional water damage restoration company. Whether or not the costs are covered in your homeowners’ insurance policy, the damage will continue to spread until the treatment is made. But here are some of the most common questions about homeowner’s insurance, rain, and water damage.
Is Water Damage from Rain Covered Under Homeowner’s Insurance?
In most cases, yes! A standard homeowner’s insurance policy will cover water damage from rain, as long as the storm had “opened up” a hole in the roof, causing the water to leak in. On the other hand, any rotten shingles or other holes in the structure that was present before the storm will usually be denied because they are considered “preventable.” The insurance adjuster will most likely tell you that the hole could have been fixed beforehand to prevent water damage.
What Happens When Rain Causes a Flood?
While most leaks are typically covered under standard homeowners’ insurance policies, if the leak had created a flood in which there is standing water, the disaster would not be covered. Insurance agencies specifically do not include flooding under their standard policies, due to the severity of the damage and the high costs involved.
For insurance to cover flood damage, the property owner would need to have flood insurance.
Does Homeowner’s Insurance Cover Other Damages from Rainstorms?
Depending on the severity of rainstorms, many other types of damage can occur to a home, including storm, wind, and hail damage. While all policies differ with various companies, homeowner’s insurance typically covers the damages caused by these natural disasters. Ultimately, natural disasters can come in many different forms, causing damages completely unforeseen by property owners.
Hail Damage. During severe storms, if hail is of a certain density, it can break windows, cause leaks, and even make dents in vehicles.
Tornado/Wind Damage. Wind gusts of over 50 mph have the power to rip off siding and roof shingles, topple over trees, and blow rocks, sticks, and other debris around. In some cases, these occurrences have left properties in critical conditions.
Lightning Damage. While severe storms are also associated with strong winds, lightning can destroy roofs, chimneys, and cars if they strike them directly. You will want to talk to your insurance company right away to see if you are eligible for this type of coverage.
Is General Wear and Tear Covered?
While homeowners’ insurance can cover various water and rain damages, they are meant for emergency situations. This means that they will not cover the damage to a home if a building material already needed to be replaced. This includes everyday wear and tear, which will be identified by your adjuster if they find that the damaged building material is old, rotten, or due for replacement before the storm occurred.
Common disasters that are not usually covered under homeowners’ insurance policies include clogged gutters and drains, old, rotten roof shingles, and rusty pipes. Be sure to have these repaired or restored when they are needed to avoid both a physical and financial disaster.
Which Water Damage Restoration Companies Does Insurance Pay For?
While water and other damages caused by rainstorms can leave your home in critical condition, it is essential to choose a water damage restoration company whose service costs are covered by your homeowner’s insurance policy. This is one of the primary questions to ask any provider during an emergency situation before signing the waiver to do the work.
You may want to consider looking at RestorationMaster. This company not only works with your insurance provider but uses advanced equipment and products to return all building materials to their original conditions from the storm. They also provide a wide variety of other restoration services, including fire damage restoration, flood cleanup, mold removal, and more. No matter the severity or extent of the damage their technicians have years of experience and training to have the property restored in a timely manner.
How Does Insurance Cover Commercial Water Damage?
Water damage is harmful to any property. It ruins building materials and personal belongings and if the damage gets bad enough, it can even cause structural damage. The longer water damage goes unattended, the worse the water damage gets. Water will continue to spread throughout the property to cause more damage, and mold can begin to grow within 24 to 48 hours of the initial damage. But while all cases of water damage are troublesome, commercial water damage, in particular, is especially concerning.
Water Damage in Commercial Buildings
When a commercial property suffers water damage, the business itself suffers. Depending on the amount of damage done, business owners may need to close their business and halt work operations for an extended period of time in order to have the damage repaired. Additionally, when a business is closed to customers, the potential for revenue is lost. Employees may also be unable to go into the space to do their work. Depending on the job, this could mean they are unable to work at all.
It can be expensive to pay for repairs and restoration for water damage, which is why it’s important to have thorough commercial water damage coverage from your insurance provider.
Water damage in commercial buildings can even be potentially hazardous to people’s health and well-being if there’s mold growth. For mold spores to grow, they need a food source and a warm, moist environment. Both can be provided in cases of water damage, because mold uses building materials like drywall as food. When mold is present, people exposed to it can suffer from negative health effects, such as irritation to eyes, nose, throat, lungs, and skin. If you have asthma or allergies, mold can have a greater negative effect on you. Because of this, it’s essential to have commercial water damage addressed right away. Otherwise, you risk harming anyone who inhabits the damaged space.
Causes of Commercial Water Damage
When it comes to water damage, the harm can be caused by various things. There are natural causes like flooding and storms and unnatural causes like faulty piping. Businesses typically see more foot traffic than residential properties, so things like toiletry, plumbing, and the HVAC system are used more heavily. This frequent usage makes them wear out quicker, so they’re more susceptible to malfunctions, such as leaky pipes, that can lead to water damage.
If your business is in an area that experiences cold temperatures, then the water pipes for your commercial property are at risk of bursting, which can also result in serious water damage. Pipe bursts happen when the water inside the pipes freezes into ice. When the water turns to ice, it expands in size and places pressure on the pipe. When the pressure becomes too much, it bursts the pipe open and spreads water throughout the space.
Insurance Coverage for Commercial Water Damage
It can be expensive to pay for cleanup and restoration for water damage, which is why it’s important to have thorough commercial water damage coverage from your insurance provider. You want to make sure your business can be helped in the event that water damage occurs. Not all commercial insurance policies are the same, though. Water damage can be sourced in so many ways and the coverage differs among available commercial insurance policies depending on the cause. You may need to add water damage coverage or get additional coverage on top of the standard policy to cover a greater range of water damage sources. When getting quotes, pay attention to what different companies offer and inquire about what the coverage options are for water damage.
Leaks and burst pipes are among two of the more common causes for commercial water damage, so business owners should especially make sure their policies cover such damage. However, slow, gradual leaks often aren’t covered by commercial property policies. This is because companies see this as negligence ― something that could have been prevented with proper maintenance unlike an accident, which happens suddenly and could not have been avoided.
Keep this all in mind when choosing what commercial insurance to get for your business. If you already have a business and commercial insurance for it, look over your policy. Review the coverage to see whether your business is protected against water damage and to what extent. Contact your insurance agent, and inquire with them what additional coverage ― if any ― you can get to further protect your business. While no business owner wants to deal with water damage, it’s better to be safe and have that insurance than to find yourself unprotected.
If your business ends up suffering from water damage, then you need to seek immediate assistance from a professional water damage cleanup and restoration service that helps restore damage in commercial properties. Professional technicians will begin their work by containing the damage to prevent it from spreading further and becoming worse. Furthermore, they have the correct equipment to properly dry your commercial property and restore or replace any damaged building materials. If mold has grown as a result of the water damage, technicians can address that problem as well.
Related articles:
Water Damage Insurance Claim Tips: What You Need to Know

About Vince Sandri
Vince Sandri is a disaster restoration content specialist with more than 12 years of experience researching, writing, and educating property owners about water damage, fire and smoke damage, mold remediation, storm damage, and other disaster recovery topics. Since 2014, he has served as the lead contributor to RestorationMaster.us, where he has developed hundreds of in-depth service pages, educational guides, and industry-focused articles for restoration professionals across the United States.
Through extensive research and ongoing collaboration with restoration contractors, Vince has built a strong foundation in the science, processes, and best practices behind property damage mitigation and recovery. His work aligns with industry standards like the IICRC and EPA guidelines, and helps homeowners, business owners, and property managers understand how disasters impact structures, what immediate steps to take, how professional restoration works, and how to prevent long-term structural and health risks.
Vince specializes in translating complex restoration procedures — including water extraction, structural drying, smoke odor removal, mold containment, and storm damage repair — into clear, actionable information that empowers readers to make informed decisions during high-stress situations. His content aligns with industry standards and focuses on safety, accuracy, and practical response strategies.
He earned his Bachelor of Arts degree from Aurora University and his master’s degree from DePaul University. Since 2012, Vince has focused on SEO-driven website content, technical service pages, and educational resources within the disaster restoration industry.
Outside of his professional work, Vince is also a musician and performs in the Chicago, IL area.